A health insurance policy may show more than one coverage amount. You may see a base sum insured, a bonus, restored cover or another enhanced amount. This can make it difficult to know how much is actually available when a claim occurs.
The answer depends on how each part of the cover is designed and when it can be used. Reading the policy schedule and benefit conditions together helps you understand the amount that can apply to a particular claim.
What Is the Base Sum Insured?
The base sum insured is the main coverage amount chosen under the policy. It is the starting pool from which eligible medical claims are usually paid. This amount appears in the policy schedule and remains subject to exclusions, sub-limits, co-payment and other conditions.
When you compare health insurance plans in India, pay attention to how much of the stated coverage comes from the base sum insured. Bonuses or other added benefits may increase the overall cover, but they can have separate conditions for use.
What Is an Enhanced Cover?
Enhanced cover is an additional amount that may sit above the base sum insured. It can come from a cumulative bonus, added benefit or restoration, depending on the policy. This amount may have its own activation rules.
It may become available only after certain conditions are met, such as using part or all of the base cover. This is why enhanced cover should be checked separately instead of assuming that the full additional amount can always be used.
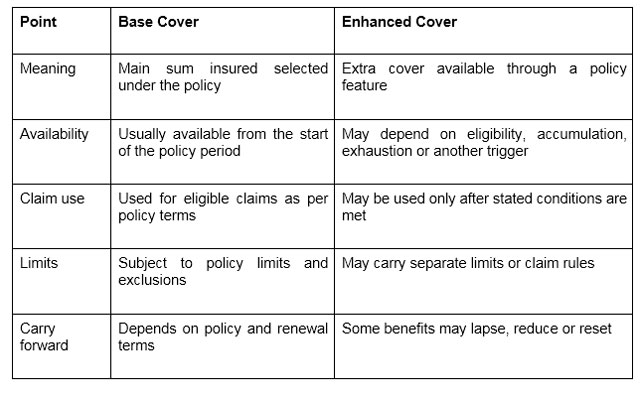
Base Cover and Enhanced Cover: What’s the Difference?
A top-up health insurance plan also provides additional protection, but it works differently. It generally becomes payable only after the applicable deductible condition is met. It should not be treated as an automatic extension of the base cover.
Does the Enhanced Cover Have Separate Limits?
Yes, enhanced cover should not be assumed to work exactly like the base sum insured. The wording may decide when it becomes available and which claims can use it.
Check whether the enhanced amount:
- Applies to the first claim or only a later claim;
- Becomes available only after another cover is used;
- Can be used for the same illness or only eligible future claims;
- Is subject to specific benefit limits or exclusions.
These conditions can change the amount available for a hospital bill.
How Does the Claim Amount Get Calculated?
The claim is not settled by simply adding every coverage figure shown on the policy. The payable amount depends on eligible medical expenses and the cover available for that claim.
The calculation may consider:
- The unused base sum insured;
- Any eligible additional cover;
- Room, treatment or benefit limits;
- Co-payment or deductible conditions;
- Non-payable or excluded expenses.
The final payable amount depends on both the claim and policy conditions.
What Happens If the Base Cover Is Exhausted?
Using the full base sum insured does not always mean the policy has no cover left. An enhanced benefit may become available if its conditions have been met.
After the base cover is exhausted:
- An eligible restoration benefit may activate;
- Accumulated bonus cover may remain available if allowed;
- Another additional cover may respond under its own terms;
- Any remaining claim amount may stay unpaid if no further eligible cover is available.
Check whether the extra amount applies to the same claim, a later claim or only after a particular trigger.
How to Check Your Actual Available Coverage
Do not rely only on the largest coverage figure shown in promotional material. Check how each part of the cover works before assuming it can be used for the same claim.
Review:
- The policy schedule for the base sum insured;
- The benefit wording for extra cover;
- The order in which different covers are used;
- Any deductible, co-payment or sub-limit;
- Whether extra cover applies to the current claim;
- The remaining balance after earlier claims.
For an ongoing claim, the insurer or claims team can confirm the amount available under the policy.
Conclusion
The amount available for a claim is not always the highest coverage figure shown in the policy. The base sum insured is the main cover, while enhanced benefits may work only after certain conditions are met. Some extra amounts may support later claims, while others have separate limits. To know what you can actually use, read the policy schedule, benefit wording and claim conditions together instead of relying only on the total cover displayed.